ServicesTerm Life Insurance
Jackson Term Life Insurance
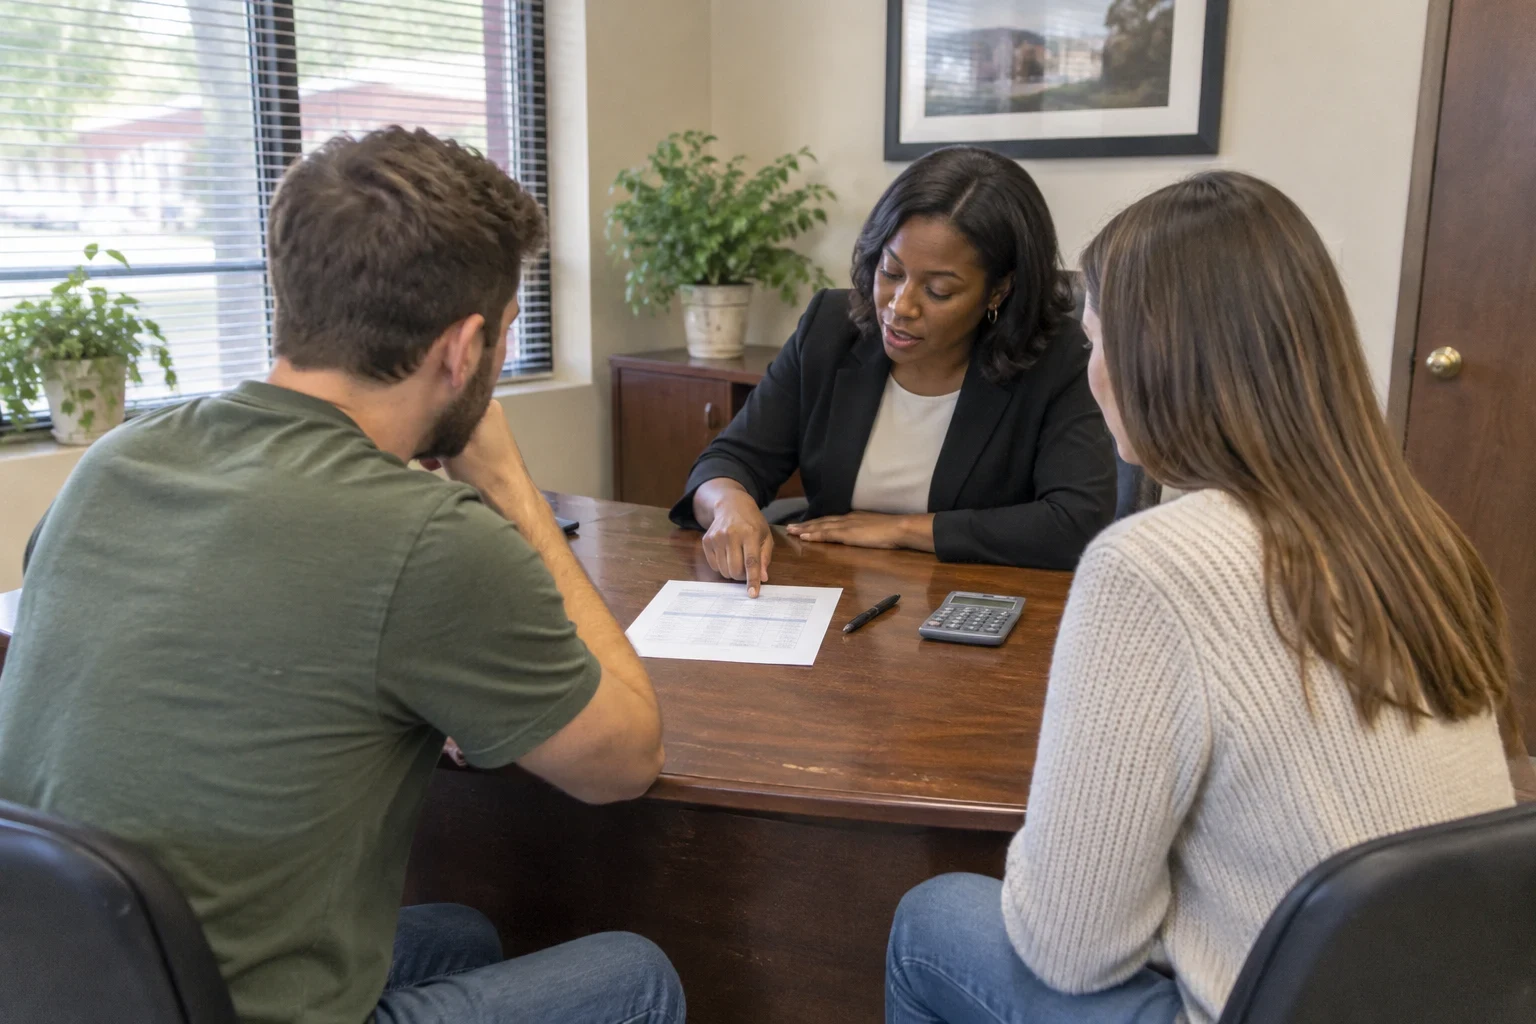
If you die while your term policy is in force, the people you named get the money. For most families, it is the lowest-cost way to protect the years when the house payment and the kids weigh the most. We help you pick how much and how long, without the jargon.
How term life works and when it makes sense
Term life covers you for a set number of years, most often 10, 20 or 30. If you die within that window, your named beneficiary gets the money. If you outlive it, the policy simply ends. It builds no cash value, which is why term costs much less than whole life for the same coverage.
That makes term a good match for a need with a known end date. A mortgage. Children who will grow up and earn their own living. A spouse who relies on your paycheck until retirement savings are large enough.
We start by reviewing what you already carry. If a work plan or older policy still fits, we tell you and just cover the gap. If an older policy costs too much for what it gives you, we explain why replacing it could be smarter, and the decision is yours.
What you get when we work together
An amount based on your actual numbers
We total your mortgage balance, other debts, the years of income your family would lose and large costs like college. Your policy is sized to that figure, not a rough guess.
A length that matches your milestones
We line the policy up with key dates, like your final mortgage payment or your youngest child's graduation. Too short and your family goes uncovered. Too long and you pay for years you likely will not need.
Options laid out next to each other
Every option appears together with its monthly cost and what it covers. Each plan is built around your needs and budget, not taken off a shelf.
Your coverage on one page
Once your policy is active, you get a single page listing what you hold, what you pay and who is covered. Keep it where your family can reach it quickly.
Someone beside your family at claim time
Your family will not file a claim by themselves. We guide them in person, from the first call until the payment arrives.
When term life is worth a look
- You got married or had a child
- Another person now depends on your paycheck. It is the most common reason people call us about term coverage.
- You just closed on a home
- A mortgage is a big debt with a fixed end date. A term policy can keep your family in the house if you are not around to make the payments.
- Your only coverage is through work
- Employer plans often pay out one or two years of salary. They usually stop when you change jobs. Many families need more, in a policy they own outright.
- Most of the bills run on your income
- If your household would be behind within a few months without your paycheck, you likely need coverage that replaces it for years, not a few weeks.
- Your current policy is outdated
- Maybe the amount was picked before the kids or the bigger house came along. Sometimes adding a second term policy is the better fix. Sometimes starting fresh is. We will tell you plainly which one fits.
From your first call to a policy in hand
- 1
You reach a real person
A local agent picks up when you call, not a phone tree. We ask a couple of short questions and book a free appointment that suits your schedule.
- 2
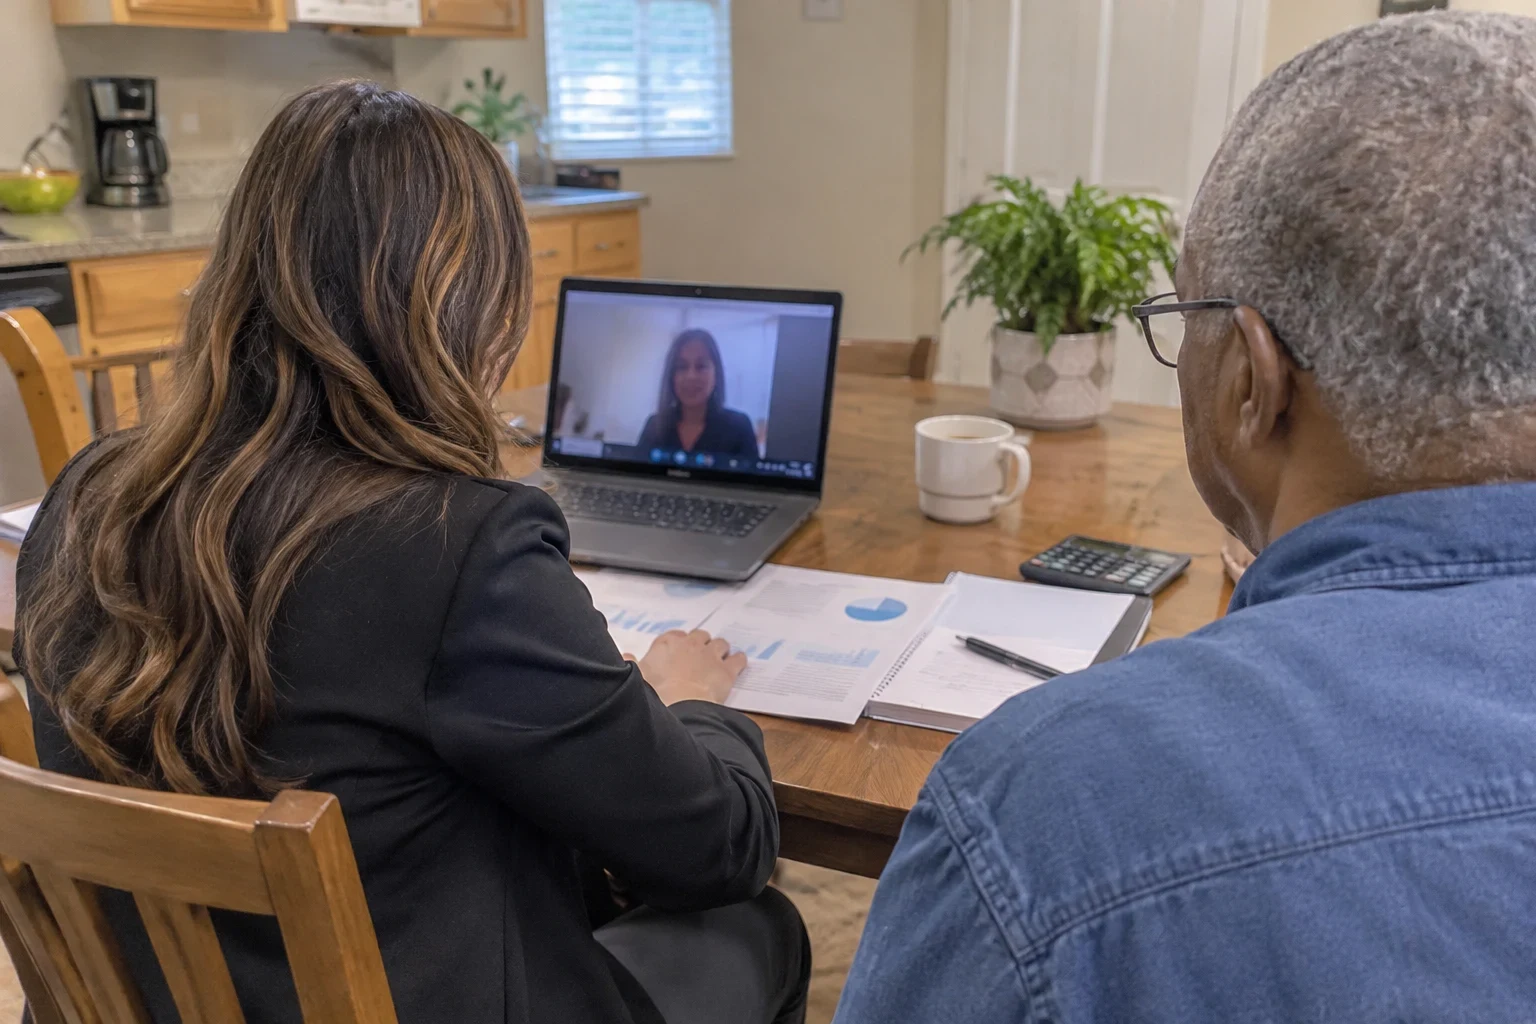
We meet at the office or by video
Together we go over your debts, your income and what you want covered. If driving in from Madison or Brandon is a pain, a video call works just as well. There is no pressure. We explain each option and you choose on your own timeline.
- 3
Health questions and the application
We go through the application questions with you at the appointment or over the phone. Depending on how old you are and how much coverage you pick, the insurer might ask for a quick exam or just rely on your health answers.
- 4
Approval and handoff
The insurer reviews your file and sets the final price. Before you sign, we go over the approved policy line by line and give you your one-page summary.
- 5
A review every year
We schedule a yearly review for you, so it is not one more thing to remember. Each year we also check your beneficiaries to make sure the money still goes where you want it.
What drives the cost of term coverage
Term is usually the least expensive life insurance, yet no two quotes match exactly. The insurer is pricing the odds of paying out before the term is up. These details move your price the most.
- Your age
- Buying younger gets you a lower rate. Putting it off a year usually means a slightly higher price for the same coverage.
- Your health and habits
- The insurer checks blood pressure, weight, past health problems and tobacco use. A smoker pays far more than a nonsmoker for the same policy.
- The coverage amount
- Higher coverage costs more. But twice the coverage does not cost twice as much, so a larger policy often gives more value per dollar.
- The length of the term
- A longer term covers you at older ages, so it costs more. Locking in 30 years runs higher each month than locking in 10.
- Optional riders
- Add-ons like a child rider or a conversion option can raise the premium slightly. We show each one's cost so you can leave off anything you will not use.
Term life questions we get often
- What happens when my term runs out?
- Your coverage stops, and so do the payments. Some policies let you renew year to year after that, but the price climbs sharply each time. Most people pass, since by then the mortgage is nearly paid and the kids support themselves.
- Can I turn my term policy into permanent coverage later?
- Many term policies come with a conversion option. It lets you move some or all of the coverage into whole life with no new medical exam, as long as you act before your policy's deadline. We flag that deadline when you buy so it does not slip past.
- Should I cancel my old policy and buy a new one?
- Most of the time, no. If your policy is fairly priced, we usually suggest keeping it and adding a second one to cover the gap. If it is too costly or ends too early, we explain why replacing it may be better. We never let an old policy lapse until the new one is active.
- Do I need a medical exam?
- That depends on your age, health history and the amount you apply for. Smaller policies can be approved on health questions alone. Larger ones often need a short exam, and the examiner can usually visit your home or office for free.
- What if my life changes after I buy?
- Call and let us know. A new baby, a move or a new job gets your coverage updated within a week of telling us. Sometimes it only takes a beneficiary change. Other times adding a policy is the better move.
See how much coverage your family needs
Bring your mortgage balance and a rough sense of your monthly bills. We work through the numbers with you and lay out the options, with nothing to sign and no pressure.